ULIP vs Term Plan Plus Mutual Fund (2026): An Honest Comparison
Last updated: 13 October 2026
Quick answer (ULIP vs Term): For most people, a term plan plus mutual fund beats a ULIP because it gives roughly ten times the life cover, full liquidity and wider fund choice. A low-cost ULIP with total premiums of ₹2.5 lakh a year or less can match it on returns, thanks to tax-free maturity. It suits disciplined savers who already have enough term cover and can stay invested 10-15 years.
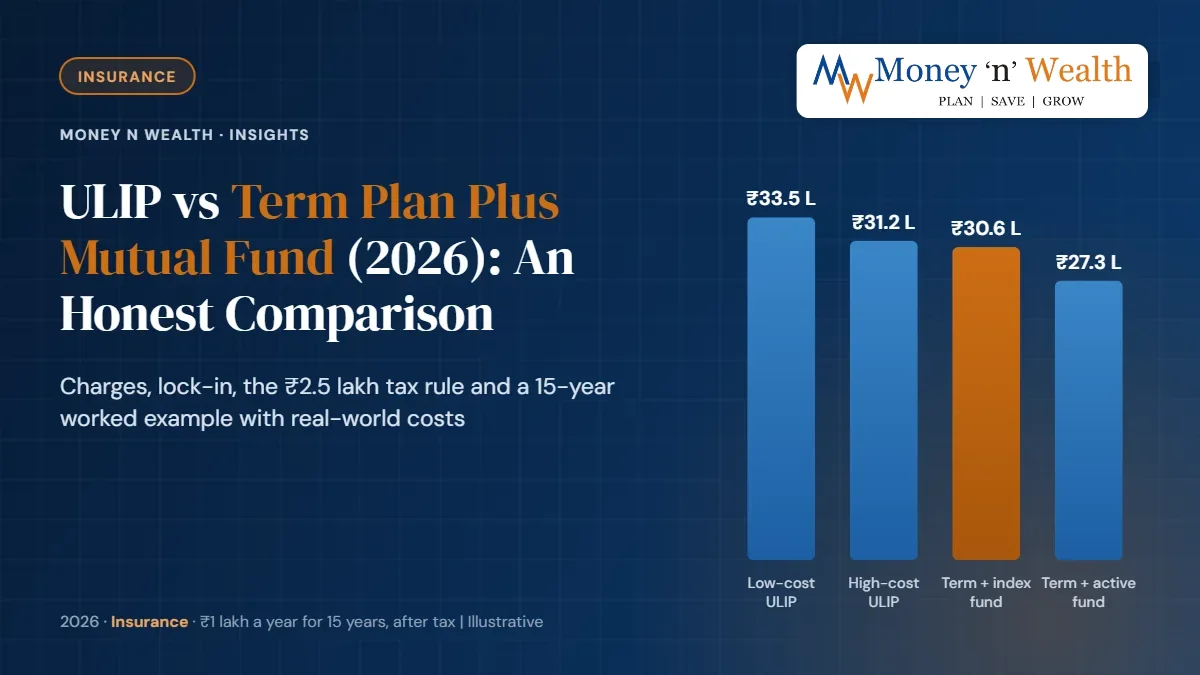
Last updated: 13 October 2026 Quick answer (ULIP vs Term): For most people, a term plan plus mutual fund beats a ULIP because it gives roughly ten times the life cover, full liquidity and wider fund choice. A low-cost ULIP with total premiums of ₹2.5 lakh a year or less can match it on returns, thanks to tax-free maturity. It suits disciplined savers who already have enough term cover and can stay invested 10-15 years. Key takeaways Cover gap: ₹1 lakh a year buys about ₹10 lakh of cover in a ULIP, versus about ₹1 crore in a term plan. Returns: in our 15-year example, a low-cost ULIP ends at ₹33.5 lakh; term plus index fund at ₹30.6-33 lakh. Tax rule: ULIPs issued from 1 February 2021 lose tax-free maturity if total ULIP premiums exceed ₹2.5 lakh a year. Lock-in: 5 years for ULIPs; most equity mutual funds have none (ELSS has 3 years). Costs matter most: a high-cost ULIP or a regular-plan active fund each costs ₹2-6 lakh over 15 years. A 30-year-old engineer in Hinjewadi has ₹1 lakh a year to save. One adviser offers a ULIP: "insurance plus market returns, tax-free". Another says buy term insurance and run a SIP. Both sound reasonable, and both camps tend to exaggerate. A ULIP (unit linked insurance plan) is a life insurance policy that invests most of your premium in market-linked funds, after deducting charges for insurance and administration. A term plan plus mutual fund splits the same job into two products: pure life cover from an insurer, and investment through a SEBI-regulated fund. This guide compares them honestly, with charges, the 2026 tax rules and a worked 15-year example. Money n Wealth distributes both insurance and mutual funds, so we have no reason to favour either. How does a ULIP work, and what does it charge? Your premium goes into a unit fund of your choice (equity, debt or balanced). The insurer deducts charges either from the premium or by cancelling units every month. Older and branch-sold ULIPs carry more of these charges; many online ULIPs now skip the premium allocation charge altogether. Premium allocation charge: a percentage of each premium kept by the insurer before investing, usually highest in the early years. Mortality charge: the cost of life cover, levied monthly on the "sum at risk" (cover minus fund value). It rises with age. Policy administration charge: a flat or rising monthly fee. Fund management charge: capped at 1.35% a year of fund value, deducted before the NAV is declared. Discontinuance charge: applies if you stop paying in the first four years, with a rupee cap of up to ₹6,000 in year 1; nil from year 5. IRDAI also caps the total drag, measured as the "reduction in yield" (the gap between gross fund return and your net return). For policies of 15 years or longer, it cannot exceed 2.25% a year at maturity. Your benefit illustration shows this figure; ask for it before you sign. Key ULIP charge caps in India: 5-year lock-in, 1.35% fund management charge, discontinuance charges up to ₹6,000 What does the 5-year lock-in actually mean? If you stop paying premiums within the first five years, your fund moves to a "discontinued policy fund" after deducting the discontinuance charge. It earns a modest debt-like return, with fund charges capped at 0.5% a year. You get the money only after the fifth policy anniversary. That is the price of the forced discipline. For an emergency, see our emergency fund guide (/insights/emergency-fund-guide-india) ; a ULIP should never be your emergency money. ULIP vs term plan plus mutual fund: the worked example We modelled a 30-year-old non-smoker investing ₹1 lakh a year for 15 years. To isolate costs and structure, every option earns the same 11% gross equity return. That number is an assumption, not a forecast; markets will deliver something different, but the gaps between options would largely remain. Option Key assumptions Life cover Corpus after 15 years (after tax) Return (IRR) Low-cost online ULIP No allocation charge; 1.35% fund charge; mortality on ₹10 L cover ₹10 lakh ₹33.5 lakh (tax-free) 9.5% High-cost ULIP Allocation 6% in year 1, 4-5% to year 5, 2% after; ₹300/month admin ₹10 lakh ₹31.2 lakh (tax-free) 8.7% Term + direct index fund ₹12,000 term premium; ₹88,000 in a 0.2%-cost index fund ₹1 crore ₹30.6 lakh (₹33.0 lakh before tax) 8.5% Term + active regular fund ₹12,000 term; ₹88,000 in a fund costing 1.6% a year ₹1 crore ₹27.3 lakh (₹29.2 lakh before tax) 7.2% The term premium of ₹12,000 a year for ₹1 crore is illustrative; actual quotes depend on age, health, term and insurer. The IRR counts the full ₹1 lakh outlay, including the term premium, so the term-plus-fund options carry the cost of ten times more cover. ULIP vs term plan plus mutual fund corpus after 15 years on ₹1 lakh a year: low-cost ULIP ₹33.5 lakh, high-cost ULIP ₹31.2 lakh, term plus index fund ₹30.6 lakh, term plus active fund ₹27.3 lakh What the numbers actually say First, a well-priced ULIP is not the disaster it was before 2010. When the premium is within ₹2.5 lakh, its tax-free maturity offsets most of its higher costs. The low-cost ULIP even finishes ahead of the term-plus-index-fund route when the fund is redeemed in one go. Second, that lead depends on tax timing. A mutual fund investor can book up to ₹1.25 lakh of long-term gains each year tax-free and reinvest, which our tax harvesting guide (/insights/capital-gains-tax-shares-tax-harvesting) explains. Do that diligently and the term-plus-index-fund corpus moves close to ₹33 lakh, level with the ULIP. Third, the ₹1 crore of cover is the real difference. If the ULIP buyer also needs ₹1 crore of protection, they must buy a term plan on top, which raises their outlay above ₹1 lakh a year. Fourth, costs dominate: a high-cost ULIP or an expensive active regular fund each gives up ₹2-6 lakh against the cheapest option. Our guide to fund costs (/insights/mutual-fund-expense-ratio-exit-load-costs) shows how to check them. How is a ULIP taxed in 2026? The ₹2.5 lakh rule The Income-tax Act 2025, in force since 1 April 2026, carries over the old section 10(10D) exemption as Schedule II, serial number 2. Maturity proceeds of a ULIP are tax-free only if two conditions hold. The yearly premium must not exceed 10% of the sum assured (for most policies issued after 1 April 2012). And, for ULIPs issued on or after 1 February 2021, your total premium across all such ULIPs must not exceed ₹2,50,000 in any year of the policy term. If you cross ₹2.5 lakh, the ULIP is treated like an equity mutual fund, provided at least 65% of its money stays in equity throughout the term. Section 198 of the new Act explicitly includes such ULIP funds in the definition of an "equity oriented fund". Long-term gains above ₹1.25 lakh a year are then taxed at 12.5%, and short-term gains at 20%. A death claim stays tax-free in every case. ULIP tax rules 2026 compared: premium up to ₹2.5 lakh tax-free, above ₹2.5 lakh taxed like equity mutual funds Two practical points follow. A ₹3 lakh-a-year ULIP has lost its main edge over a mutual fund, while keeping the lock-in and higher costs. And the ₹2.5 lakh limit is aggregate, so two ₹1.5 lakh ULIPs bought after February 2021 breach it together. Premiums paid can still be claimed under section 123 (the old 80C) in the old tax regime, within the ₹1.5 lakh cap; the new regime, now the default, offers no such deduction. See our mutual fund capital gains guide (/insights/capital-gains-tax-mutual-funds-2026) for the equity rates in detail. When can a ULIP make sense? We would consider a ULIP only when all of these hold: Your protection is already sorted: you hold adequate term cover (often 10-15 times income; see how much term cover you need (/insights/term-insurance-advisor-pune) ) and health insurance. The premium is ₹2.5 lakh a year or less across all ULIPs, so the maturity is tax-free. The product is genuinely low-cost: nil or minimal premium allocation charge, a low fund charge, and a reduction in yield you have seen in writing. You will stay 10-15 years: the charge structure only evens out over the long run. You value forced discipline: some investors redeem SIPs in every market fall. The lock-in and tax-free internal switching (moving from equity to debt as a goal nears) help them. A ULIP can also fit a specific goal where a lump sum must reach the family even if the earner dies, through riders such as premium waiver in child plans. Compare that against a term plan plus a separate fund before deciding. When is a term plan plus mutual fund clearly better? You need large cover cheaply. This is the most common case for young families with a home loan. You may need the money within five years , or your income is uncertain (for example, IT professionals worried about layoffs). Your investable amount is above ₹2.5 lakh a year , so a ULIP's tax advantage is gone. You want wider choice. Mutual funds offer hundreds of schemes, index options and transparent daily portfolios across AMCs; a ULIP limits you to one insurer's funds. You may want to change course. Stopping a SIP costs nothing; stopping a ULIP in year two costs a discontinuance charge and five years of waiting. Choose the fund carefully too. Our example shows a costly active regular fund trailing a low-cost ULIP. Our index funds guide (/insights/index-funds) and the note on direct vs regular plans (/insights/direct-vs-regular-mutual-funds-what-the-higher-return-claim-leaves-out) cover that choice. If your goal is tax-saving under the old regime, ELSS (/insights/elss-funds-new-tax-regime-2026) offers a shorter three-year lock-in. Decision checklist for choosing between a ULIP and a term plan plus mutual fund Already holding a ULIP? What to do Do not surrender it in panic. Check four things: the policy year, the remaining charges, your fund choice and your total premium. Past year 5? Discontinuance charges are nil, and most front-loaded charges are behind you. The remaining cost is mainly the fund and mortality charges, so continuing is often reasonable. Inside year 5? Stopping premiums only moves money to the discontinued fund until year 5. Compare the charge you would pay against the extra charges of continuing. Wrong fund? Use the free switches to move between equity and debt funds. Switching inside a ULIP is not a taxable sale. Too little cover? Buy a separate term plan regardless of the ULIP decision. Older traditional (non-ULIP) policies are a different question, covered in our guide on whether to surrender an old traditional policy (/insights/surrender-old-traditional-life-policy) . For guaranteed plans, read how to work out their real IRR (/insights/guaranteed-return-endowment-plan-real-irr) . Red flags when someone sells you a ULIP Returns quoted as "₹X lakh at maturity" without the assumed growth rate. IRDAI requires illustrations at both 4% and 8% gross returns. Comparisons with FDs that ignore the five-year lock-in and charges. Single-premium ULIPs sold as "pay once, get insurance and returns" with cover of just 1.25 times the premium. Pressure to surrender an existing policy to fund a new one, which resets the charges. Our article on mis-selling red flags (/insights/mis-selling-red-flags-insurance-investments) lists more, and you can review both products on our insurance (/products/insurance) and mutual fund (/products/mutual-funds) pages. Related reading Insurance planning in India: term, health and life (/insights/insurance-planning-guide-india) Guaranteed-return and endowment plans: the real IRR (/insights/guaranteed-return-endowment-plan-real-irr) Should you surrender an old traditional policy? (/insights/surrender-old-traditional-life-policy) XIRR vs CAGR vs absolute return (/insights/xirr-vs-cagr-vs-absolute-return) How to build a ₹1 crore corpus with SIPs (/insights/build-1-crore-corpus-sip-calculator-guide) Frequently Asked Questions Is a ULIP better than a mutual fund? Not generally. A low-cost ULIP with premiums within ₹2.5 lakh a year can match a mutual fund's after-tax return over 15 years, because its maturity is tax-free. But it locks money for five years, limits fund choice to one insurer and provides little life cover. A mutual fund wins on flexibility and transparency; a ULIP suits only disciplined, long-term savers with adequate term cover. Is ULIP maturity tax-free in 2026? Yes, if the yearly premium is within 10% of the sum assured and, for ULIPs issued from 1 February 2021, your total ULIP premium is ₹2.5 lakh a year or less. This exemption now sits in Schedule II of the Income-tax Act 2025. Above ₹2.5 lakh, gains are taxed like equity funds: 12.5% on long-term gains over ₹1.25 lakh. Death benefits stay tax-free. What is the lock-in period of a ULIP? Five years. If you stop paying premiums earlier, the fund value (minus a capped discontinuance charge) moves to a discontinued policy fund and is paid out only after the fifth policy year. Partial withdrawals are also allowed only after five years. Equity mutual funds generally have no lock-in, though exit loads may apply for the first year. How much life cover does a ULIP give? Usually ten times the annual premium for buyers under 45, so a ₹1 lakh premium buys about ₹10 lakh of cover. The same money can buy a ₹1 crore term plan for a healthy 30-year-old at around ₹12,000 a year, leaving ₹88,000 to invest. If you need large cover, a ULIP alone is not enough. What are the main charges in a ULIP? Premium allocation, mortality, policy administration, fund management (capped at 1.35% a year) and discontinuance charges, plus rider and switching charges where applicable. IRDAI caps the combined effect, measured as the reduction in yield; for policies of 15 years or more it is 2.25% a year at maturity. Your benefit illustration shows the figure for your policy. Should I surrender my ULIP and start a SIP? Only after checking the policy year. Before year 5, surrendering triggers a discontinuance charge and your money waits until year 5 anyway. After year 5, the front-loaded charges are already paid, so continuing a low-cost ULIP is often fine. Surrender if charges remain high or the fund is poor, and buy term cover first if you need it. Can I claim tax deduction on a ULIP premium? Under the old tax regime, yes: ULIP premiums qualify under section 123 of the Income-tax Act 2025 (the old section 80C), within the ₹1.5 lakh overall limit. The new tax regime, the default from 2026-27, does not allow this deduction. Do not buy a ULIP only for the deduction; the maturity tax treatment and costs matter more. Sources: Income Tax Department: Schedule II, Income-tax Act 2025 (https://www.incometaxindia.gov.in/w/schedule-ii-9) ; Income Tax Department: section 198 (https://www.incometaxindia.gov.in/w/section-198-76) ; IRDAI policyholder portal: circulars (https://policyholder.gov.in/web/guest/circulars) ; Morningstar India: ULIP charges (https://morningstar.in/posts/28760/5-ulip-charges-you-must-know.aspx) ; Value Research: discontinuing a ULIP (https://www.valueresearchonline.com/stories/200588/the-rules-about-discontinuing-a-unit-linked-plan/) ; Ditto: ULIP charge caps (2026) (https://joinditto.in/articles/life-insurance/ulip-charges/) . Worked examples are Money n Wealth calculations. Is your ULIP or term-plus-SIP plan the right fit? The answer depends on your cover, tax regime and existing policies. Talk to Money n Wealth (/contact) for an insurance review. This article is for general educational purposes only and does not constitute financial advice. Figures and examples are illustrative. Please consult a qualified financial adviser for guidance specific to your situation. Money n Wealth (Predics Fintech Services Pvt Ltd) is an AMFI-registered Mutual Fund Distributor (ARN-121995) and APMI-registered PMS Distributor (APRN07444); it is not a SEBI-registered investment adviser and may earn distribution commission on investments made through it. Insurance is the subject matter of solicitation.
Frequently Asked Questions
Is a ULIP better than a mutual fund?
Not generally. A low-cost ULIP with premiums within ₹2.5 lakh a year can match a mutual fund's after-tax return over 15 years, because its maturity is tax-free. But it locks money for five years, limits fund choice to one insurer and provides little life cover. A mutual fund wins on flexibility and transparency; a ULIP suits only disciplined, long-term savers with adequate term cover.
Is ULIP maturity tax-free in 2026?
Yes, if the yearly premium is within 10% of the sum assured and, for ULIPs issued from 1 February 2021, your total ULIP premium is ₹2.5 lakh a year or less. This exemption now sits in Schedule II of the Income-tax Act 2025. Above ₹2.5 lakh, gains are taxed like equity funds: 12.5% on long-term gains over ₹1.25 lakh. Death benefits stay tax-free.
What is the lock-in period of a ULIP?
Five years. If you stop paying premiums earlier, the fund value (minus a capped discontinuance charge) moves to a discontinued policy fund and is paid out only after the fifth policy year. Partial withdrawals are also allowed only after five years. Equity mutual funds generally have no lock-in, though exit loads may apply for the first year.
How much life cover does a ULIP give?
Usually ten times the annual premium for buyers under 45, so a ₹1 lakh premium buys about ₹10 lakh of cover. The same money can buy a ₹1 crore term plan for a healthy 30-year-old at around ₹12,000 a year, leaving ₹88,000 to invest. If you need large cover, a ULIP alone is not enough.
What are the main charges in a ULIP?
Premium allocation, mortality, policy administration, fund management (capped at 1.35% a year) and discontinuance charges, plus rider and switching charges where applicable. IRDAI caps the combined effect, measured as the reduction in yield; for policies of 15 years or more it is 2.25% a year at maturity. Your benefit illustration shows the figure for your policy.
Should I surrender my ULIP and start a SIP?
Only after checking the policy year. Before year 5, surrendering triggers a discontinuance charge and your money waits until year 5 anyway. After year 5, the front-loaded charges are already paid, so continuing a low-cost ULIP is often fine. Surrender if charges remain high or the fund is poor, and buy term cover first if you need it.
Can I claim tax deduction on a ULIP premium?
Under the old tax regime, yes: ULIP premiums qualify under section 123 of the Income-tax Act 2025 (the old section 80C), within the ₹1.5 lakh overall limit. The new tax regime, the default from 2026-27, does not allow this deduction. Do not buy a ULIP only for the deduction; the maturity tax treatment and costs matter more.
Is your ULIP or term-plus-SIP plan the right fit?
The answer depends on your cover, tax regime and existing policies. Talk to Money n Wealth for an insurance review.