Pune Rental Yields by Area 2026: Is Buy-to-Let Still Worth It?
Last updated: 13 October 2026
Quick answer: The gross rental yield in Pune is about 2.8% to 3.4% for a typical 2BHK in areas such as Hinjewadi, Wakad and Wagholi, based on ANAROCK's quoted rents and prices. After vacancy, maintenance, property tax and income tax, the investor keeps about 1.4% a year. Buy-to-let works only if prices grow 5% or more a year, or you need the flat yourself later.
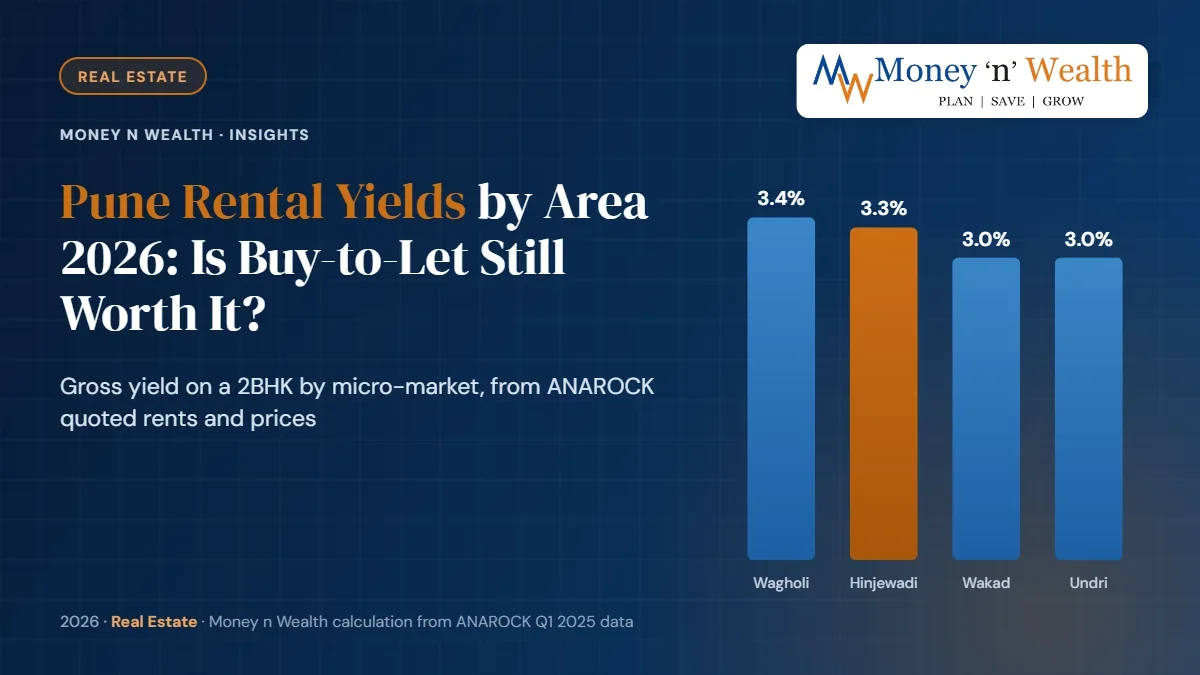
Last updated: 13 October 2026 Quick answer: The gross rental yield in Pune is about 2.8% to 3.4% for a typical 2BHK in areas such as Hinjewadi, Wakad and Wagholi, based on ANAROCK's quoted rents and prices. After vacancy, maintenance, property tax and income tax, the investor keeps about 1.4% a year. Buy-to-let works only if prices grow 5% or more a year, or you need the flat yourself later. Key takeaways Gross yield: about 3.3% in Hinjewadi and 3.0% in Wakad, on 2BHK quoted rents and prices. City trend: ANAROCK's Pune yield rose from 3.1% in 2020 to 3.85% in early 2024. Rents vs prices: Hinjewadi rents rose 57% from end-2021 to end-2024, prices 37%. Net reality: 1.4% after costs and 30% slab tax in our worked example. 10-year return: 3.8% to 6.6% a year post-tax, depending on price growth. A 2BHK in Hinjewadi costs around ₹1.05 crore and rents for about ₹28,500 a month. That is ₹3.42 lakh of rent a year on a ₹1 crore-plus asset, or 3.3% before a single expense. A bank FD pays more than double that. So why do so many Pune investors still buy a second flat to rent out? This guide sets out what rental yields really are in Pune's main micro-markets, using published data from ANAROCK and Global Property Guide, and explains how we calculated them. It then works through costs, tax on rental income and the full 10-year return, so you can judge whether buy-to-let still earns its place. What is rental yield, and how is it calculated? Rental yield is the annual rent a property earns, expressed as a percentage of its price. Gross yield uses rent before any costs. Net yield subtracts vacancy, maintenance, property tax, repairs and brokerage, and is best measured against everything you paid, including stamp duty. The formula is simple: gross yield = monthly rent × 12 ÷ price × 100. A ₹1 crore flat renting at ₹25,000 a month has a gross yield of 3%. Rental yield is only one half of property returns; the other half is price growth, or capital appreciation. What is the rental yield in Pune by area? No official body publishes locality-level rental yields for Pune. National Housing Bank's RESIDEX tracks prices, not rents. So we built yields from the best published figures available, and we show the method so you can check it. Method: ANAROCK's Pune report for January–March 2025 gives the quoted monthly rent range for a standard 1,000 sq ft 2BHK and the average quoted price per sq ft in five micro-markets. We took the mid-point of each rent range, multiplied by 12, and divided by the price of a 1,000 sq ft flat. Quoted figures are asking prices and asking rents, so actual deals may differ. Micro-market 2BHK rent (₹/month) Quoted price (₹/sq ft) Gross yield range Mid-point yield Wagholi 19,000–29,000 8,500 2.7%–4.1% 3.4% Hinjewadi 23,500–33,500 10,500 2.7%–3.8% 3.3% Wakad 25,000–32,300 11,400 2.6%–3.4% 3.0% Undri 17,000–24,500 8,400 2.4%–3.5% 3.0% Talegaon Dabhade 12,000–16,000 6,000 2.4%–3.2% 2.8% Source: ANAROCK Residential Market Viewpoints, Pune Q1 2025; yields are Money n Wealth calculations. Rents and prices have moved since, but yields change slowly because both tend to rise together. Bar chart of rental yield in Pune by area: Wagholi, Hinjewadi, Wakad, Undri and Talegaon A second source: listing-based yields for 2026 Global Property Guide, which surveys listings twice a year, published Pune data in May 2026. It divides median asking rents by median asking prices. Its 2-bedroom gross yields were 4.91% in Hadapsur, 4.17% in Wagholi, 4.00% in Hinjewadi, 3.83% in Kharadi, 3.69% in Undri and 3.65% in Baner. Its all-Pune average across sizes was 5.20%, lifted by small studios and 1BHKs. These figures run about 0.5 to 1 percentage point higher than our ANAROCK-based estimates, partly because listing samples skew to smaller, older and cheaper units. Treat the two sources as a range. A sensible planning assumption for a new 2BHK in a popular Pune suburb is a gross yield of 3% to 4%, with 1BHKs and older buildings at the higher end and premium areas such as Baner at the lower end. Has Pune's rental yield been rising? Yes, gently. ANAROCK's city-wide series put Pune's average residential yield at 3.3% in 2019, 3.1% in 2020, 3.5% in 2022, 3.6% in 2023 and 3.85% in January–March 2024. Rents rebounded sharply after offices reopened, while prices rose more slowly. Line chart of Pune average rental yield rising from 3.1% in 2020 to 3.85% in Q1 2024 The gap is starkest in IT corridors. ANAROCK data reported in March 2025 showed that from end-2021 to end-2024, rents rose 57% in Hinjewadi and 65% in Wagholi, while capital values rose 37% in both. Bar chart comparing rent growth and price growth in Hinjewadi and Wagholi, Pune Price growth has since slowed. NHB RESIDEX showed Pune's house price index up just 3.5% in the year to December 2025, the latest release and among the slowest of the large cities, and ANAROCK reported Pune housing sales down 15% year on year in April–June 2026, to about 13,090 units. Our rent vs buy in Pune (/insights/rent-vs-buy-pune) model uses the same NHB data. How do Pune's yields compare with other cities? Global Property Guide's 2026 survey puts India's average gross yield at 5.16%, Bengaluru at 5.01% and Mumbai at 3.74%, with Pune at 5.20% on its method. Whatever the source, Indian residential yields sit well below home loan rates, which crossed 8% after RBI's October 2026 repo hike. That is unusual by global standards, where yields close to or above borrowing costs are common in many rental markets. In India, buyers have historically accepted low yields because they expected strong price growth. When price growth slows, as in Pune since 2025, the low yield becomes the main story. What does it cost to own a rented flat in Pune? Gross yield ignores the costs that fall on the landlord. Here is a realistic annual list for our ₹1.05 crore Hinjewadi example, with rent at ₹28,500 a month. Item (year one) Assumption Amount Gross rent ₹28,500 × 12 ₹3,42,000 Vacancy One month a year between tenants −₹28,500 Brokerage One month's rent every two years −₹14,250 Society maintenance ₹3.50 per sq ft a month on 1,000 sq ft −₹42,000 Property tax Illustrative; let-out homes do not get owner-occupier concessions −₹15,000 Repairs and repainting Averaged per year −₹15,000 Leave and licence agreement, police verification Registration and stamp duty, averaged −₹3,000 Net rent before tax ₹2,24,250 Net rent of ₹2.24 lakh is 2.1% of the flat's price. But you also paid 7% stamp duty, the ₹30,000 registration fee and, say, ₹3 lakh for basic furnishing, taking total cost to about ₹1.16 crore. On that, the net yield is 1.9%. Our Maharashtra stamp duty and RERA checklist (/insights/buying-flat-maharashtra-rera-stamp-duty-checklist) lists every purchase cost. In Maharashtra, a leave and licence agreement must be registered, which is quick online, and Pune police require tenant verification. Skipping either puts you on the wrong side of the law and weakens your hand in a dispute. How is rental income taxed in 2026? Rent is taxed as income from house property under the Income-tax Act, 2025. You start with the rent actually received, subtract municipal taxes you paid, then deduct a flat 30% for repairs and upkeep, whatever you actually spent. Interest on a loan for the let-out flat is deductible in full. The remainder is added to your income and taxed at your slab rate. Our example: rent received ₹3,13,500 (after one vacant month) minus ₹15,000 property tax gives ₹2,98,500. After the 30% deduction, ₹2,08,950 is taxable. In the 30% slab with 4% cess, tax is about ₹65,200. Post-tax: net rent of ₹2.24 lakh minus ₹65,200 tax leaves about ₹1.59 lakh, or 1.4% of total cost. New vs old regime: both allow the 30% deduction and full interest on a let-out property. Only the old regime lets a resulting loss reduce salary income, up to ₹2 lakh a year, with the rest carried forward for eight years. In the new regime, excess interest is simply lost. TDS by tenants: an individual tenant paying more than ₹50,000 a month must deduct 2% TDS, now under section 393 of the 2025 Act, filed on Form 141. Chart showing Pune rental yield falling from 3.3% gross to 1.4% after costs and tax Our detailed guide to rental income tax and the 30% deduction (/insights/rental-income-tax-30-percent-deduction-india) covers joint owners, arrears and vacant periods. For the loan side, see home loan tax benefits under both regimes (/insights/home-loan-tax-benefits-old-new-regime) . Is buy-to-let in Pune still worth it? To answer that, we need the total return: rent plus price growth, after all costs and taxes. We modelled our Hinjewadi flat bought with cash, held for 10 years, with rents and costs rising 5% a year and a sale at the end after 1% brokerage and 12.5% long-term capital gains tax. Post-tax 10-year returns from buy-to-let in Pune at different price growth rates Yearly price growth Flat value after 10 years Post-tax annual return (IRR) 3.7% (slow-growth case, close to Pune's latest 3.5%) ₹1.51 crore 3.8% 5.5% (Pune, compounded over four years) ₹1.79 crore 5.3% 7% ₹2.07 crore 6.6% At recent Pune price growth, an all-cash rental flat earns roughly what a bank FD earns after tax for someone in the 30% slab, but with far less liquidity, more effort and concentration in a single asset. If prices compound at 7%, the return improves but still trails what long-term equity investors have historically sought, without the diversification. What about buying with a home loan? Borrowing makes the cash flow worse. An 80% loan of ₹84 lakh at 8.25% costs about ₹6.9 lakh of interest in year one, against ₹2.24 lakh of net rent. You fund the gap of more than ₹4.6 lakh, plus principal, from salary every year. Leverage magnifies gains only when prices grow faster than the loan rate, which Pune has not delivered recently. Read prepay your home loan or invest (/insights/prepay-home-loan-or-invest) before adding a second loan. When buy-to-let can still make sense You will use the flat later: for retirement, a child's college years or a parent nearby, renting it out meanwhile simply offsets the holding cost. You buy well below market: a distress resale at a 10–15% discount changes the maths more than any rent increase. Small units in demand pockets: 1BHKs near IT parks and colleges tend to earn higher yields, as both data sources show. It fits your asset mix: property is under a third of your net worth, and you hold liquid investments for emergencies. Alternatives for rental-style income If the goal is regular income from real estate, listed REITs own rent-paying offices and malls, trade daily and must distribute most of their cash flow. Our guides on REITs and InvITs (/insights/reits-invits-guide-india) , SM REITs (/insights/sm-reits-small-medium-reits-guide) and fractional real estate (/insights/fractional-real-estate-india-benefits-tax-risks) compare their yields, tax and risks. For a broad view, see real estate vs mutual funds (/insights/real-estate-vs-mutual-funds-where-should-your-next-20-lakh-go) . Related reading Rent vs buy in Pune: a 10-year model (/insights/rent-vs-buy-pune) Rental income tax: 30% deduction, municipal tax, loan interest (/insights/rental-income-tax-30-percent-deduction-india) Buying a flat in Maharashtra: RERA and stamp duty checklist (/insights/buying-flat-maharashtra-rera-stamp-duty-checklist) Tax on property sale: sections 54, 54F and 54EC (/insights/tax-on-property-sale-section-54-54f-54ec) REITs and InvITs: income from offices and roads (/insights/reits-invits-guide-india) Retirement income: pension, rent or SWP? (/insights/retirement-income-pension-rent-or-swp-25-years) Frequently Asked Questions What is a good rental yield in Pune? For a new 2BHK in a popular suburb, a gross yield of 3% to 4% is typical as of 2026, based on ANAROCK and Global Property Guide data. Anything above 4% is good for Pune and usually comes from 1BHKs, older buildings or a below-market purchase price. Net yields after costs are generally 1 to 2 percentage points lower. Which area in Pune gives the highest rental yield? On ANAROCK's Q1 2025 quoted figures, Wagholi (about 3.4%) and Hinjewadi (3.3%) led among the five areas covered. Global Property Guide's May 2026 listings put Hadapsur highest for 2-bedroom flats at 4.91%. Premium areas such as Baner show lower yields because prices are high relative to rents. How much tax do I pay on rent from a Pune flat? Rent received minus municipal tax is reduced by a flat 30% standard deduction and any home loan interest on that flat. The balance is taxed at your slab rate. On ₹3.13 lakh of rent with ₹15,000 property tax, about ₹2.09 lakh is taxable, which costs roughly ₹65,000 in the 30% slab. Is it better to buy a flat for rent or invest in mutual funds? Purely on numbers, a Pune rental flat bought with cash has returned roughly 4% to 6.5% a year post-tax in our model, depending on price growth. Diversified mutual funds offer liquidity and small ticket sizes but carry market risk. The right answer depends on your goals, other assets and need for liquidity, not on yield alone. Do I need to register a rent agreement in Pune? Yes. In Maharashtra, leave and licence agreements must be registered, and this can be done online with biometric verification. A small stamp duty and registration fee apply. Pune police also require tenant verification. A registered agreement protects both landlord and tenant if there is a dispute over rent, deposit or eviction. Should I buy a 1BHK or 2BHK for rental income in Pune? Smaller units usually earn higher yields because rents do not fall in proportion to price. Global Property Guide's 2026 Pune data shows 1-bedroom gross yields of about 5% to 6.8% in areas like Hinjewadi and Hadapsur, against roughly 3.7% to 4.9% for 2-bedrooms. However, 2BHKs often see stronger resale demand from families. Sources: ANAROCK Residential Market Viewpoints, Pune Q1 2025 (https://websitemedia.anarock.com/media/Residential_Market_Viewpoints_Pune_Q1_2025_dc7f7f51df.pdf) ; Global Property Guide, India rental yields (May 2026) (https://www.globalpropertyguide.com/asia/india/rental-yields) ; RealtynMore on ANAROCK rental data (Nov 2023) (https://realtynmore.com/?p=87383) ; RealtynMore on ANAROCK rental data (Apr 2024) (https://realtynmore.com/?p=90092) ; RealtynMore on ANAROCK capital vs rental growth (Mar 2025) (https://realtynmore.com/?p=96470) ; Business Standard on ANAROCK capital and rental growth (https://www.business-standard.com/amp/industry/news/capital-appreciation-outpaced-growth-in-key-markets-between-2021-24-report-125031700289_1.html) ; Punekar News on Pune housing sales, Q2 2026 (https://www.punekarnews.in/?p=238875) ; Income Tax Department FAQs on forms under the Income-tax Rules, 2026 (https://www.incometaxindia.gov.in/faqs-and-guidance-notes-on-forms-as-per-income-tax-rules-2026) . Yields by area, the cost table and 10-year returns are Money n Wealth calculations. Thinking of a second flat for rental income? Whether property, REITs or a mix of funds suits you depends on your goals, tax slab and existing assets. Talk to Money n Wealth (/contact) for a free portfolio review. This article is for general educational purposes only and does not constitute financial advice. Figures and examples are illustrative. Please consult a qualified financial adviser for guidance specific to your situation. Money n Wealth (Predics Fintech Services Pvt Ltd) is an AMFI-registered Mutual Fund Distributor (ARN-121995) and APMI-registered PMS Distributor (APRN07444); it is not a SEBI-registered investment adviser and may earn distribution commission on investments made through it.
Frequently Asked Questions
What is a good rental yield in Pune?
For a new 2BHK in a popular suburb, a gross yield of 3% to 4% is typical as of 2026, based on ANAROCK and Global Property Guide data. Anything above 4% is good for Pune and usually comes from 1BHKs, older buildings or a below-market purchase price. Net yields after costs are generally 1 to 2 percentage points lower.
Which area in Pune gives the highest rental yield?
On ANAROCK's Q1 2025 quoted figures, Wagholi (about 3.4%) and Hinjewadi (3.3%) led among the five areas covered. Global Property Guide's May 2026 listings put Hadapsur highest for 2-bedroom flats at 4.91%. Premium areas such as Baner show lower yields because prices are high relative to rents.
How much tax do I pay on rent from a Pune flat?
Rent received minus municipal tax is reduced by a flat 30% standard deduction and any home loan interest on that flat. The balance is taxed at your slab rate. On ₹3.13 lakh of rent with ₹15,000 property tax, about ₹2.09 lakh is taxable, which costs roughly ₹65,000 in the 30% slab.
Is it better to buy a flat for rent or invest in mutual funds?
Purely on numbers, a Pune rental flat bought with cash has returned roughly 4% to 6.5% a year post-tax in our model, depending on price growth. Diversified mutual funds offer liquidity and small ticket sizes but carry market risk. The right answer depends on your goals, other assets and need for liquidity, not on yield alone.
Do I need to register a rent agreement in Pune?
Yes. In Maharashtra, leave and licence agreements must be registered, and this can be done online with biometric verification. A small stamp duty and registration fee apply. Pune police also require tenant verification. A registered agreement protects both landlord and tenant if there is a dispute over rent, deposit or eviction.
Should I buy a 1BHK or 2BHK for rental income in Pune?
Smaller units usually earn higher yields because rents do not fall in proportion to price. Global Property Guide's 2026 Pune data shows 1-bedroom gross yields of about 5% to 6.8% in areas like Hinjewadi and Hadapsur, against roughly 3.7% to 4.9% for 2-bedrooms. However, 2BHKs often see stronger resale demand from families.
Thinking of a second flat for rental income?
Whether property, REITs or a mix of funds suits you depends on your goals, tax slab and existing assets. Talk to Money n Wealth for a free portfolio review.